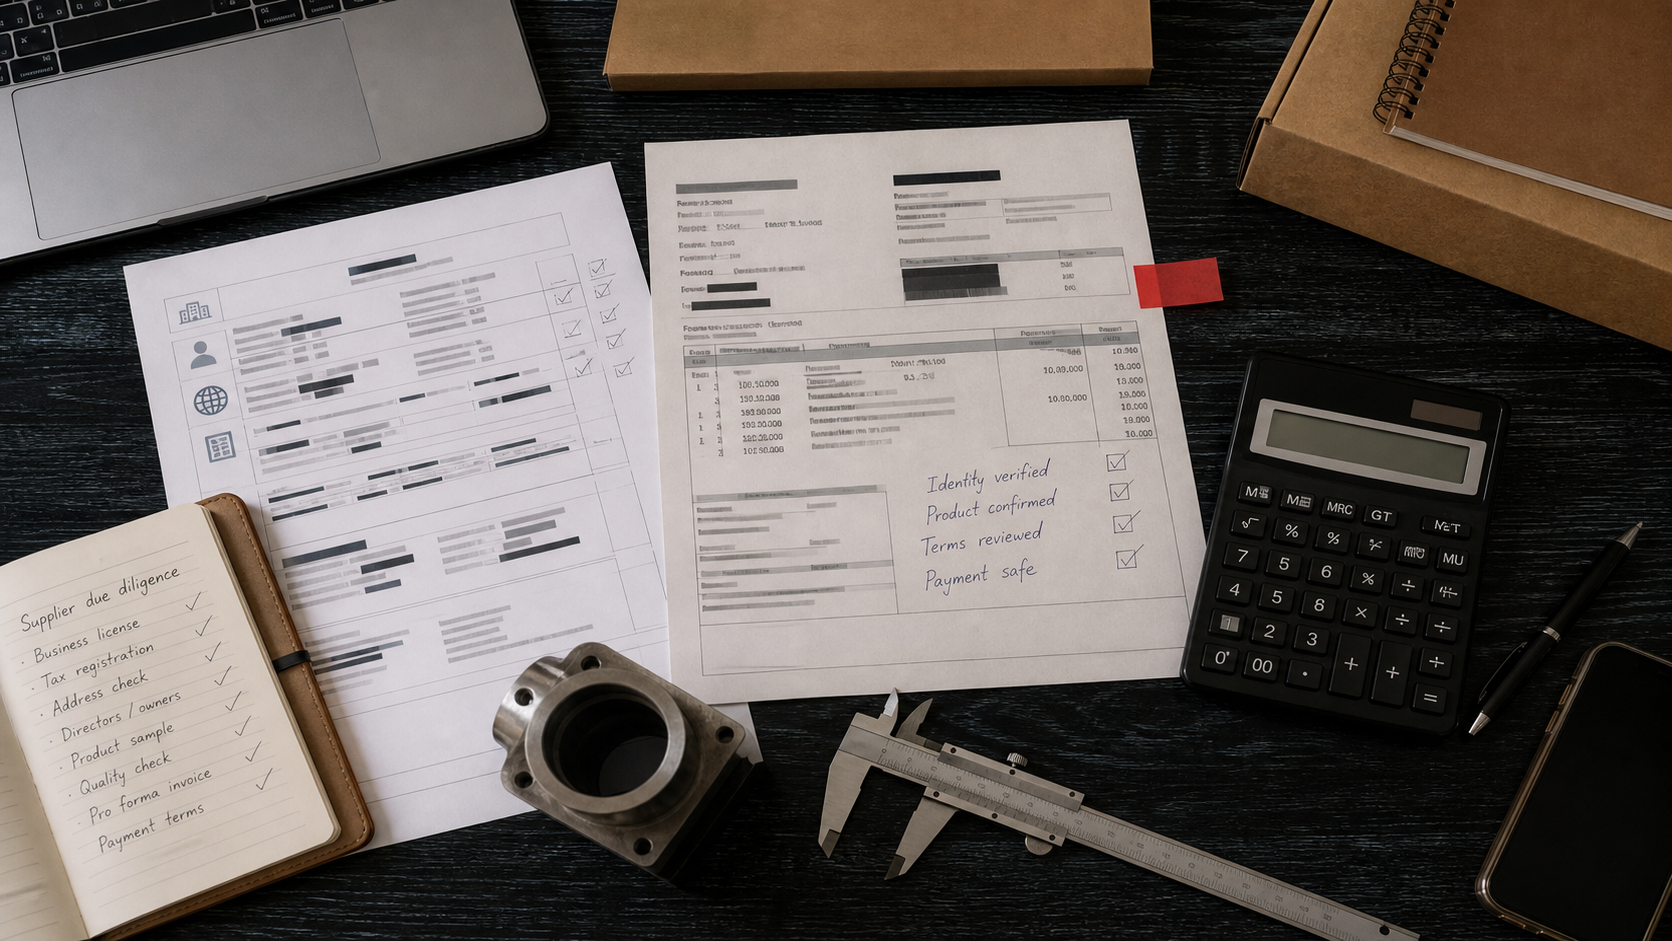
The dangerous moment is not when you first find a supplier. It is when the pro forma invoice arrives and the deposit is due.
My first check is not the product catalogue. It is whether the legal name on the quotation matches the entity that will invoice me and receive the payment. A quick search that confirms a business name exists is only one small part of supplier verification.
You need to verify four separate things:
- a legal entity exists;
- the person emailing you is allowed to act for it;
- the business can make or supply the product you need; and
- the invoice and payment instructions lead to the same business you checked.
Those are related. They are not interchangeable.
A company registration can show that an entity is on a public register. It does not prove that the salesperson works there, that the business owns a factory, that today’s stock exists, or that the bank account on the invoice belongs to that entity.
I use a seven-stage check. Start with a fast desktop pass. Then deepen the work before the first meaningful payment. If a point does not join up, I pause the order instead of explaining it away for the supplier.
1. The seven checks before payment
This is the sequence I recommend.
- Confirm the legal entity and trading identity.
- Confirm the contact’s authority.
- Check that the business can actually supply the product.
- Test a sample against a written specification.
- Make the commercial terms comparable and complete.
- Verify the bank details and limit payment exposure.
- Decide whether the order needs an audit, inspection or specialist compliance work.
I do not treat this as a seven-box test. Evidence builds a picture. A single clean-looking document should not outweigh a serious mismatch somewhere else.
2. 1. Confirm the legal entity and trading identity
I ask for the supplier’s full registered name, registration number, registered address, trading address and tax number. Put those details into one working record. Do not rely on a logo, a marketplace profile or an email signature.
Then use the official register for the country where the supplier says it is established. This is where I begin the evidence file, not where I end the decision.
For a UK company, Companies House’s free search service lets you check the company name, number, registered office, status, filing history and certain officer information. Companies House explains that it makes the public company data it holds available through the service. That is useful evidence about the registered entity. It is not a credit opinion, a quality audit or a guarantee of trading performance.
For an EU supplier that gives you an EU VAT number, check it in the European Commission’s VIES VAT-number validation service. VIES validates VAT numbers for cross-border EU transactions. A result can be a useful consistency check. It does not prove that the company owns its stock, is financially sound or is authorised to sell a brand.
Country registers differ. Search for the relevant national business register rather than relying on a paid data page that may be old or incomplete. Save a PDF or screenshot of the result and record the date. Registry data changes.
Now compare every field you have collected. I want these fields to tell one coherent story:
- Does the legal name on the register match the name on the quotation and invoice?
- Does the registered address make sense alongside the claimed warehouse or factory address?
- Is the VAT number associated with the same country and legal entity?
- Has the company recently changed name, address or status?
- Is the email domain consistent with the company’s public website and other contact details?
Small differences have innocent explanations. A trading name can sit above a different legal entity. A group company can invoice for a factory. A distributor can sell stock from a separate warehouse.
I would not reject a supplier because one address is different. A trading name, group company or separate warehouse can all be legitimate. I would pause the order until the supplier explains the relationship in writing and the documents agree.
The problem is not that a structure is complicated. The problem is when the explanation changes, or when nobody can say which entity is contracting with you.
A company number is not a payment check
Imagine a supplier calls itself “Northstar Homeware”. The UK register shows that Northstar Homeware Ltd exists and is active. So far, so good.
But the quotation is issued by “Northstar Trading”, the VAT number belongs to a different entity, and the bank beneficiary is an individual’s name in another country. That is not a minor admin error to ignore because the company number was real.
I would ask for a revised quotation naming the legal seller, then ask for a written explanation of the relationship between the entities and the beneficiary. If it cannot do so cleanly, I would stop here. A real company can still be impersonated, misrepresented or used as cover for an unrelated payment request.
3. 2. Confirm that the contact can represent that entity
The next question I ask is simple: who is the person asking you to pay?
Start with these basics:
- Use the phone number and website found independently, not only the contact details in the quote.
- Ask for a short video call from the warehouse, showroom or office when the order justifies it.
- Check that the sender uses a company domain rather than a free email account. This is a signal, not proof. Small, legitimate businesses may use free email.
- Ask the contact to confirm their role, the contracting entity and whether they are authorised to change bank details.
- For a higher-value order, call a publicly listed number and confirm the payment instructions with someone other than the person who sent the invoice.
I look for a chain of confirmation. The name on the quote, email domain, company phone number, video call, invoice and payment confirmation should all point to the same business.
I treat a late bank-detail change as a new verification event. Do not reply to the email that announced it. Use the independently sourced contact route and ask for confirmation.
4. 3. Verify product and operational capability
“We can supply it” is not enough for me.
First, establish what the supplier actually is. I approach a manufacturer, wholesaler, distributor and sourcing agent differently because each gives you a different level of control and responsibility. A wholesaler may suit a small trial order but have no authority to alter packaging or grant brand permission.
Ask direct questions:
- Are you the manufacturer, an authorised distributor, a wholesaler, or an agent?
- Which legal entity will sell the goods to us?
- Is the product made to order or supplied from stock?
- What is the normal production or dispatch lead time, and what starts that clock?
- What is the minimum order quantity by product, colour, size and packaging format?
- Which parts are subcontracted?
- Can you provide product specification, packaging details and current compliance documents where relevant?
I want answers specific enough to expose operational reality. “Lead time is two weeks” is vague. “Fourteen working days from approved artwork and deposit, plus three days to dispatch from our Rotterdam warehouse” is something I can test and put into an order plan.
Request evidence that fits the claim. For stock, I would ask for a dated stock report, batch photographs or a live warehouse video. For manufacturing, I would ask for a facility address, production schedule and an explanation of subcontracting. For authorised resale, I would ask for a letter of authorisation or a verifiable relationship with the brand.
I do not confuse documents with proof of a current capability. A factory certificate might be genuine and still not cover the exact product, site or period you care about. A warehouse photo might be real and still show somebody else’s stock. The question I ask is always: what does this evidence support, and what would still need checking?
If goods will cross borders, your product, origin and route can affect duty, procedures and restrictions. The European Commission’s Access2Markets tool is a starting point for product-by-product trade information. It does not validate a supplier. Use it to understand the import side of your decision, not to certify the seller.
5. 4. Evaluate the sample against a written specification
The sample is where a promising conversation becomes a product decision.
I would not order a sample with a message that says only “please send one”. Write down what you are approving. That can be a simple specification for a straightforward product:
- product name and SKU;
- dimensions and tolerances;
- materials, colour and finish;
- function or performance requirement;
- pack quantity and packaging;
- labels, barcodes and inserts;
- photographs or drawings; and
- the test or inspection points that matter to you.
I give the sample a reference number. Record who sent it, when it was received, and any changes the supplier says it includes. Take your own photographs.
Then assess it against the written specification. I check function, measurements, packaging and labelling before I approve it. Does it work? Are measurements within your tolerance? Is the packaging retail-ready? Does the label meet the needs of the market you plan to sell into?
An approved sample proves only that you received and accepted that sample. It does not prove that a later production batch will be identical. I tie sample approval to the purchase order. If the exact details matter, keep a signed or otherwise identified reference sample and say in the order what happens if production differs from it.
For regulated categories, a sample check is not a substitute for the right testing, technical file, declaration or responsible-person arrangement. Requirements depend on the product and the markets in which you place it. Get category-specific advice before treating a document as sufficient.
The next step is a written sample-evaluation process that records what you received, what you tested and what the approved version must match.
6. 5. Check the commercial terms before you compare the price
A low unit price can hide an expensive order.
The way I compare quotations is to normalize the terms first. Before deciding that one supplier is cheaper, make the quotes comparable. Put the following side by side:
- exact product specification and quantity;
- currency and quote validity;
- Incoterm and named place;
- packaging, tooling, samples, testing and artwork costs;
- production and dispatch lead time;
- payment schedule;
- defect, return and replacement terms; and
- what happens if delivery is late or goods differ from the approved sample.
The Incoterm needs both a rule and a named place. “EXW” or “DDP” on its own is not enough to understand the handover point and cost allocation. Use the current ICC Incoterms® rules as the reference point, and make sure the term used in your quote is actually appropriate for the route and transport mode.
If a supplier cannot state the contracting entity, product, price, delivery point and payment terms clearly on a quotation or pro forma invoice, I do not think you have a stable basis for payment.
Compare supplier quotations line by line, then calculate the landed cost before you approve the order.
7. 6. Verify bank details and limit payment risk
This is the stage where I apply the most discipline, because it is hardest to reverse.
I make sure the bank beneficiary name is the legal seller on the invoice, or that there is a documented and credible explanation for the difference. A parent company, finance company or authorised payment provider can be legitimate. You still need to understand the relationship before you pay.
My rule is a call-back verification for first payments and every bank-detail change. Call a number obtained independently and ask for the beneficiary, bank country, account ending and invoice reference. Keep a brief note of who confirmed it and when.
Then reduce the size of the irreversible decision. I would rather make a smaller, controlled commitment than rely on a comforting explanation after the money has gone.
For a first order, that may mean:
- buying a sample first;
- placing a smaller paid trial instead of a full launch order;
- agreeing staged payments linked to defined milestones;
- arranging a pre-shipment inspection before the final balance; or
- using an appropriate protected payment method where both parties accept it.
There is no universally safe payment term. The right structure depends on order value, product complexity, relationship history and the evidence you already have. A payment method has its own terms and limits; read them before relying on it.
8. 7. Decide when a desktop check is not enough
I move to an audit, inspection or specialist review when the downside is material. Typical triggers include:
- a large first order;
- a bespoke or private-label product;
- a safety-sensitive or regulated category;
- unfamiliar production country or supply chain;
- a claim that the supplier owns a factory or holds a particular certification; or
- a discrepancy that has an explanation but still leaves you uneasy.
An audit looks at a site or management system at a point in time. A pre-shipment inspection looks at a sample of a completed or near-completed production run. Scope, sampling, timing and independence matter.
Write the decision down. For example: “Order value is £8,000. Product is non-regulated homeware. Identity and sample checks are clear. We will place a 30% deposit, inspect before final payment, and keep the first order below three weeks of expected sales.”
That is a more useful record than “supplier checked”.
9. An evidence matrix you can actually use
I use this as the first page of a supplier file. Add a date and a link or saved copy for every item.
| Evidence | What it supports | What it does not prove | Follow-up action |
|---|---|---|---|
| Official business-register result | A registered entity exists; certain public details and status | That the contact represents it, that it is solvent, or that it can supply your product | Match the legal name, number and address to quote and invoice |
| VIES VAT validation | A VAT number is valid for the relevant EU cross-border purpose at the time checked | Quality, stock, brand authorisation or payment ownership | Save result; check it matches the legal seller |
| Company-domain email | The sender may be connected to the company’s communications | Authority, ownership or a safe bank account | Call independently sourced company number |
| Video call from warehouse or factory | The contact can show a location and some operations | That the location is owned, current stock is yours, or production will meet spec | Ask product-specific questions; verify address and sample |
| Product sample | You received a particular example of the product | That mass production will match it | Put the specification and reference-sample process in the purchase order |
| Bank beneficiary confirmation | The business confirms a set of payment details | That a later change is genuine or that delivery is guaranteed | Reconfirm any change through a separate channel |
| Third-party inspection report | Findings within its stated scope, time and sample | Every unit’s quality or the supplier’s overall reliability | Read the scope, sampling and date before releasing payment |
The pattern matters more than the quantity of paperwork. I would take one independent record plus a product-specific observation over five supplier-issued PDFs that repeat the same claim.
10. Red flags that should pause the order
I pause and resolve the issue when I see combinations such as:
- the legal name, VAT number, invoice name and bank beneficiary do not align;
- the supplier refuses a call-back, video call or reasonable request to explain its role;
- a new bank account appears just before payment, especially in another country;
- the claimed manufacturer cannot answer basic product or production questions;
- photos, certificates or product information are reused in a way that conflicts with the supplier’s story;
- the offer is far below comparable quotes but the supplier cannot explain why;
- pressure to pay today replaces a clear explanation of terms; or
- a supplier asks you to ignore a compliance, labelling or documentation question.
One item may have a reasonable answer. Several unresolved items are a decision. That is where I would stop the order, not try to negotiate the concern away.
11. A 30-minute first pass, then the deeper pre-order check
The 30-minute first pass
- Create a record for the supplier and request its legal name, number, address, VAT number and contact details.
- Search the relevant official register and, where appropriate, VIES.
- Compare the names and addresses with the website, quote and email domain.
- Ask what role the supplier plays and whether goods are stock or made to order.
- Request a current quotation, product specification and sample process.
- Mark every mismatch as open. Do not pay while an open mismatch affects the contracting entity or bank details.
This is enough to decide whether to continue. I would not treat it as enough to approve a large transfer.
The deeper pre-order check
Before a first meaningful payment, add these steps:
- Confirm the person and payment details through an independent contact route.
- Assess the sample against a written specification.
- Normalize the quotation, including delivery point, Incoterm, testing, packaging and payment terms.
- Calculate landed cost, not just unit price.
- Decide whether an audit, inspection or specialist compliance review is proportionate.
- Set the first-order payment and inspection plan in writing.
- Save the evidence, decision and re-check date in one place.
Re-check the supplier when something material changes: a new entity, new bank account, new production site, new regulated product, or a much larger order.
12. What to do next
Verify the entity. Then verify the person. Test the product. Make the payment route match the seller. I escalate when the cost of being wrong is larger than the cost of one more check.
That is how I approach supplier vetting. It does not eliminate every risk. It makes the decision conscious before your money leaves the account.
13. Frequently asked questions
How do I know if a wholesale supplier is legitimate?
There is no single test. Check the legal entity in the official register, confirm the contact independently, assess the product and make sure the invoice and bank beneficiary align. A company-register or VAT result is helpful evidence, not a guarantee.
Is a VAT number enough to verify a supplier?
No. For EU cross-border VAT numbers, VIES can validate the number for that purpose when it is available. It does not prove that the supplier is reliable, owns stock, is authorised by a brand or controls the bank account you have been given.
Should I pay a deposit to a new supplier?
A deposit can be normal, particularly for made-to-order goods. Before paying, verify the seller and bank details, tie the payment to a written order, and reduce exposure with a sample, small trial, staged payment or pre-shipment inspection where practical.
Do I need a factory audit for every new supplier?
No. An audit becomes more useful when the order is large, the product is bespoke or regulated, the supplier makes significant capability claims, or the downside of failure is high. A lower-value stock order may need less than a private-label product that must meet specific safety requirements.
What is the biggest red flag when paying a supplier?
A mismatch between the legal seller, the invoice and the bank beneficiary deserves immediate attention. Verify any payment-detail change through a separately sourced phone number or another independent channel before you transfer money.
This article is a commercial due-diligence guide, not legal, tax, product-safety or financial advice. Product and route-specific obligations can change. Check the relevant authority or obtain qualified advice before placing goods on a market.